A change in Washington could alter which credit score your mortgage lender pulls — and how much that score costs.
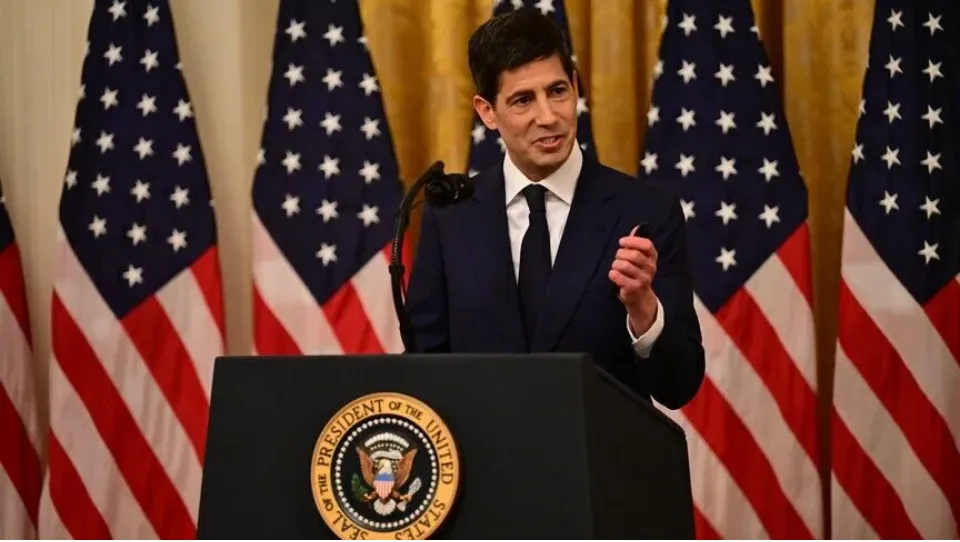
Federal Housing Finance Agency Director Bill Pulte instructed Fannie Mae and Freddie Mac on Thursday to approve all lenders to use VantageScore 4.0, effective immediately, expanding a rollout that had previously involved 50 lenders.
The change does not eliminate FICO from mortgages. Lenders delivering eligible loans to Fannie Mae and Freddie Mac can use VantageScore 4.0 as an alternative to Classic FICO. The current process still requires tri-merge credit reporting.
But investors immediately treated the wider choice as a threat to Fair Isaac’s mortgage-scoring business.
FICO shares closed Friday at $932.26, down $186.67, or 16.68%, from Thursday’s $1,118.93 close. The company finished with a market capitalization of about $20.1 billion and sits within a 52-week range of $870.01 to $1,998.01.
Your Mortgage Lender Now Has Another Score to Choose From
Pulte said the initial rollout had reached 50 lenders delivering loans and instructed Fannie and Freddie to open VantageScore to all lenders “effective immediately.”
VantageScore said Friday that its 4.0 model had already been used as the sole score on more than 9% of mortgages securitized by Fannie Mae and Freddie Mac since May 1, 2026. That figure is VantageScore’s own measurement of adoption.
For a borrower, the practical change is that a lender handling a conventional mortgage intended for one of the government-sponsored enterprises is no longer confined to the traditional FICO route.
It does not mean every lender will immediately switch. Nor does it mean a borrower’s FICO score has suddenly become irrelevant.
It means lenders now have another approved scoring model available when deciding how to process eligible mortgages.
The Price Difference Explains the Market Reaction
The fight is not only about how credit risk is measured. It is also about what lenders pay to obtain the score.
Experian and TransUnion announced earlier this year that VantageScore 4.0 mortgage-origination scores would be available for $0.99 per score.
FICO’s traditional 2026 per-score model charges $10 per score through tri-merge resellers. FICO also offers a performance-based alternative charging $4.95 per score plus a fee when a loan closes.
That difference is why Washington’s decision matters beyond credit-scoring methodology. A cheaper approved alternative gives lenders leverage over one of the costs embedded in originating a mortgage.
The Mortgage Bankers Association warned before the latest change that lenders were seeing credit-reporting costs rise by roughly 40% to 50% on average for 2026.
FICO Was Not the Only Stock Hit
The selloff spread to the credit bureaus.
Equifax closed Friday at about $177.05, down 6.37%, while TransUnion finished at $79.88, down 5.93%, according to market data.
That followed another warning from Pulte aimed at Equifax, Experian and TransUnion. He accused the three bureaus of overcharging Americans and said FHFA is “seriously considering” moving toward a bi-merge system, along with other changes.
That distinction is important: bi-merge has not been adopted. The existing tri-merge requirement remains in place.
Pulte has also described FICO’s position as a “monopoly” and claimed its score price has risen 1,800% since 2020. Those are Pulte’s characterizations, not independent findings.
What Changes for a Mortgage Borrower Now?
The immediate answer is choice at the lender level.
FICO remains accepted. VantageScore 4.0 is now available to all eligible lenders using the Fannie Mae and Freddie Mac channel. And the two models can produce different scores because they use different methodologies.
For consumers, that could eventually affect both which number appears in the underwriting process and how much of the credit-reporting bill is passed through at origination.
Friday’s $186.67 collapse in FICO shares shows how seriously investors took that possibility.
Washington did not abolish the FICO score. It made the alternative much harder for mortgage lenders to ignore.